We're having the wrong conversations about Interest Rates...
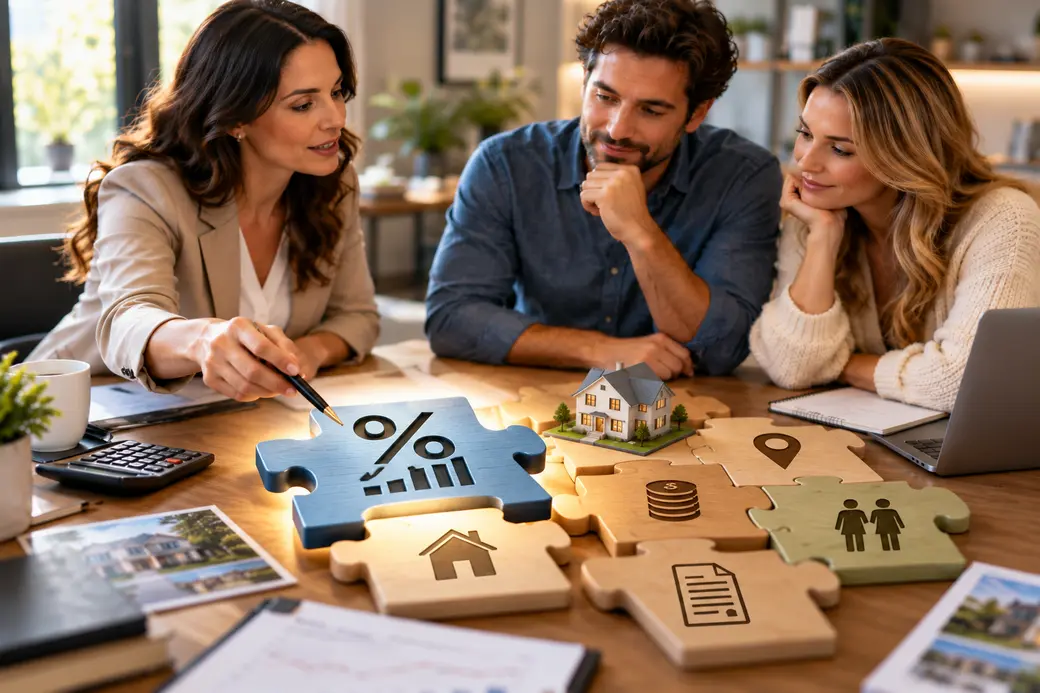
Interest Rates Are Only One Piece of the Puzzle
Interest rates are high.
There’s no reason for us to dance around that.
They affect affordability. They affect monthly payments. And for some buyers, they absolutely can be the reason buying a home doesn’t make sense right now.
But I think we’ve made a mistake in the way we talk about them.
We’ve taken one piece of the home-buying equation and allowed it to become the entire conversation.
And our clients deserve better than that.
They deserve better than “date the rate, marry the house.”
They deserve an actual conversation.
We’ve Seen This Before
Think back to 2020 and 2021.
Rates were sitting around 2% and 3%, but nobody was talking about how incredible the rates were. Everyone was talking about home prices.
I remember hearing over and over again:
“There’s no way houses are worth this much.”
“I’m not paying that.”
“Prices have to come back down.”
The problem at that time wasn’t the interest rate. The problem was the price.
Today, most of those buyers would probably love the opportunity to go back and buy at those prices.
That’s not because buying in 2021 was automatically the right decision for everybody.
It’s because one variable never tells the whole story.
And right now, the variable making all the noise is interest rates.
Ask Better Questions
So when a buyer tells us, “Rates are too high,” I think our job is to go deeper.
What does that actually mean for you?
Is the payment outside your budget?
What payment would make you comfortable?
What would rates actually have to be for you to reach that payment?
What are you trying to accomplish by buying a home in the first place?
How long do you expect to stay there?
What happens if you continue renting for another five years?
Those are much better questions than throwing out a slogan and hoping it gets someone off the fence.
Because the answer may actually be, “You shouldn’t buy right now.”
And that’s okay.
Maybe we help them find a rental and build a plan to buy later.
Maybe their lifestyle doesn’t make homeownership the right fit.
Maybe they truly cannot afford the payment.
Our job isn’t to convince someone to buy a house.
Our job is to understand, educate and advise them so they can make the best real estate decision for their situation.
The Market Is Already Solving Part of the Problem
We also have to be willing to show buyers the entire picture.
Because while rates are creating one challenge, they’re also creating opportunities in other parts of the transaction.
Buyers have leverage right now.
We’re seeing seller concessions, price negotiations, builder incentives and rate buydowns that were almost nonexistent when buyers were fighting each other for houses.
I currently represent a builder offering $15,000 in buyer incentives.
I personally have a property where I’m offering $10,000.
Why?
Because the market adjusts.
When one part of the equation becomes more difficult, opportunities often show up somewhere else.
That doesn’t magically make a payment affordable.
But those opportunities deserve to be part of the conversation.
Refinancing Is an Option, Not the Plan
The same goes for refinancing.
Could rates come down later and create an opportunity to refinance? Sure.
But I would never tell someone to buy a house today because they can refinance it later.
If you’re signing up for that mortgage, you need to be comfortable making that payment for the next 30 years.
Refinancing should be viewed as a future opportunity, not the strategy that makes today’s purchase work.
We Have to Help People Think Longer Term
I think we also need to help people think beyond this month.
A lot of people are making financial decisions through a very short-term lens.
What does this payment look like today?
What does rent cost today?
What can I afford this month?
Those things matter.
But so does asking what life looks like five or ten years from now.
If I rent for the next five years, what will my rent look like?
If I own for the next five years, what could my equity look like?
What are my long-term goals?
What am I actually trying to build?
Sometimes affordability is about income and interest rates.
Sometimes it’s also about the choices we’re making with our money.
People decide every day that they can afford the new vehicle, eating out several nights a week, vacations or other lifestyle expenses while simultaneously deciding that homeownership is too expensive.
That doesn’t mean those choices are wrong.
It means they’re choices.
And part of our job is helping people understand the tradeoffs behind them.
There Will Always Be a Cost
There has always been a cost to owning a home.
There always will be.
The payment objection isn’t new.
The thing creating that payment has simply changed.
Right now, it’s interest rates.
Five years ago, it was rapidly rising home prices.
The next market will have its own challenge.
There will probably never be a moment where price, rate, inventory, competition and somebody’s personal finances all line up perfectly.
That’s why our job can’t be to wait for the perfect market.
And it certainly can’t be to convince everybody that now is the perfect time to buy.
Our job is to understand the entire equation.
Then help our clients understand it too.
Interest rates deserve a seat at the table.
They just don’t deserve every seat.
A reminder to feed your fire,
Lyle
Categories
Recent Posts